Fan site payment processors: who accepts AI adult content in 2026
Stripe and PayPal will shut down an adult AI site. Here is who will actually process your payments, what it costs, and what the card networks now require for AI content.
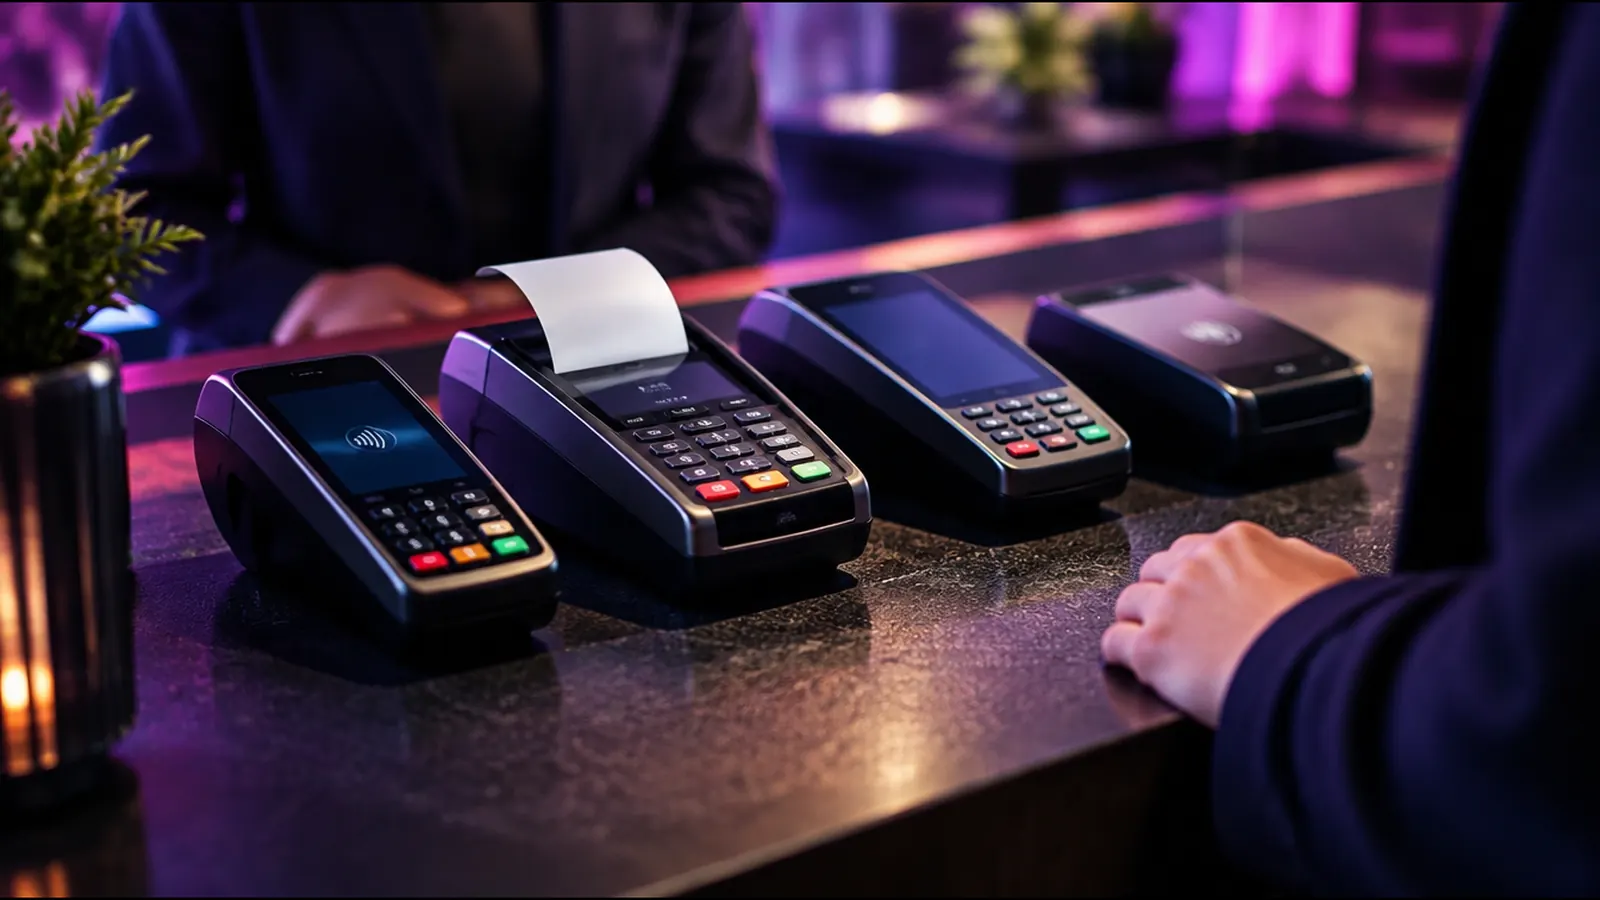
Fan site payment processors that accept adult and AI-generated adult content are a short list: adult-specialist billers such as CCBill, Segpay, Epoch and Verotel, a handful of high-risk gateways, and crypto as a backup rail. Stripe and PayPal prohibit it. Expect higher fees, a rolling reserve, card brand registration and strict content rules.
That answer surprises a lot of first-time operators. They build a beautiful AI companion site, wire up a mainstream checkout, and find out weeks later that the account is frozen and the balance is held. This guide is for affiliates, agencies, creators and would-be operators who want to get billing right the first time. It covers which processors will actually take you, what they charge, what the card networks now require for AI content, and how to structure a payment stack that survives a bad month.
Which payment processors accept adult fan sites?
Start with who will not take you, because that rules out most of the payment tools people already know.
Stripe lists adult content as prohibited. Its restricted businesses page names pornography and mature content designed for sexual gratification, pay-per-view, adult live chat features and, explicitly, "any artificial-intelligence generated content" that meets those criteria. An AI girlfriend site with explicit chat or image unlocks falls squarely inside that wording.
PayPal is just as clear for digital products. Its policy on sexually oriented goods and services does not permit sexually oriented digital goods or content delivered through a digital medium, and it names downloadable pictures, videos and website subscriptions as examples. That covers the core revenue of a fan site.
The processors that do accept this business fall into three groups:
- Adult-specialist billers. CCBill, Segpay, Epoch and Verotel act as the merchant of record or payment facilitator for adult sites. They underwrite adult risk every day, provide hosted checkouts, recurring billing, cancellation flows and customer support, and handle card brand registration on your behalf.
- High-risk gateways and acquirers. Independent sales organizations and high-risk acquiring banks can open a direct merchant account (MID) in your company's name. Rates can be better at volume, but underwriting is stricter and you carry more of the compliance work yourself.
- Alternative rails. Crypto gateways, some bank transfer schemes and stored-value wallets. Useful as a second or third option, rarely enough on their own.
How much do adult payment processors charge?
Most adult billers do not publish a rate card. CCBill's pricing page, for example, asks merchants to contact sales for processing rates. What it does publish is the card brand registration cost that every high-risk merchant pays on top: $950 a year for Visa and $1,000 a year for Mastercard.
Verotel is one of the few billers whose terms are public. Its merchant agreement sets out several mechanics worth understanding because the rest of the industry uses similar ones:
- An annual registration fee of EUR 500 on Basic accounts, waived if volume is at least EUR 100 a week at renewal.
- A rate that resets every Saturday based on your average weekly euro volume over the previous four weeks, so the more you process, the less you pay.
- Recurring transactions priced at the normal rate plus 1.5 percentage points.
- A holdback of 10% of customer charges for 26 weeks against potential chargebacks.
- Positive invoice balances paid 14 days after the invoice date.
Here is how the main cost lines compare across rail types. Treat the ranges as a planning guide, not a quote; your actual price depends on volume, chargeback history, geography and how the processor rates your content.
| Cost line | Adult-specialist biller | Direct high-risk MID | Crypto gateway |
|---|---|---|---|
| Processing rate | Highest, quoted privately, falls with volume | Lower at scale, quoted privately | Around 1% on published plans (for example NOWPayments) |
| Card brand registration | Usually passed through to you | Paid by you | Not applicable |
| Rolling reserve | Common (Verotel: 10% for 26 weeks) | Common, negotiated | Usually none |
| Chargeback exposure | Yes, with fees per dispute | Yes, plus card network monitoring | No card chargebacks |
| Compliance work | Shared, biller runs much of it | Mostly yours | Light on payments, but tax and KYC still apply |
| Conversion | Best for mainstream buyers | Best for mainstream buyers | Low; most buyers will not pay in crypto |
A worked example: what the reserve does to cash flow
Fees get the attention, but reserves are what strain a young site. Take an illustrative site billing $30,000 a month in card sales on a 10% rolling reserve held for 26 weeks, the structure in Verotel's public agreement.
- Each month, $3,000 goes into the reserve.
- Nothing comes back until the first month's holdback ages out after 26 weeks.
- By the end of month six, roughly $18,000 is sitting in reserve, money you have earned but cannot spend on traffic, content or payroll.
- After that the reserve stays roughly flat as old holdbacks release and new ones are taken, as long as volume is stable. If volume grows, the reserve keeps growing with it.
That $18,000 is working capital you need to fund from somewhere else. Operators who scale paid traffic quickly feel this hardest, because ad networks want to be paid on short terms while the processor is holding a slice of every sale for half a year. Model it before you launch, not after.
What Visa and Mastercard require from AI adult sites
Whichever processor you use, the card networks set the rules underneath it. Two changes matter most for AI companion and fan site operators.
Mastercard's adult content standards
Mastercard's specialty merchant rules for adult content took effect on October 15, 2021. As CCBill summarizes them, merchants must verify and document the age and identity of content providers and everyone depicted, keep written consent, review content before publication, handle complaints about illegal or nonconsensual content within seven business days, offer a way for people to request removal, and avoid marketing or search terms that suggest nonconsensual activity or child exploitation. Billers ask merchants to attest to compliance.
For a fully synthetic AI character there is no human performer to verify, but the same rules still bite. Your processor will want to see pre-publication moderation, a removal process, clear adult-only characters, and no prompts, tags or marketing that imply minors or nonconsent. If your generated characters resemble real people, expect the processor to ask how you prevent that.
Visa's integrity risk rules now name AI content
Visa's Integrity Risk Program treats adult content as a high-integrity-risk category. LegitScript reports that Visa's updated standards require merchant category code 5967 for adult content, "including AI-generated adult content," and that merchants without that code may be treated as miscoded and face enforcement.
In plain terms: you cannot run an explicit AI companion site under a generic software or subscription category and hope nobody notices. Miscoding is one of the fastest ways to lose a merchant account, and it can follow you to the next application.
Dispute thresholds are tightening
Visa's Acquirer Monitoring Program (VAMP) folds fraud reports and disputes into one ratio. According to Chargeback Gurus' summary of Visa's changes, merchant enforcement began on October 1, 2025, the excessive threshold was set at 2.2% through March 31, 2026, and it dropped to 1.5% from April 1, 2026, with an $8 fee per dispute and fraud report for merchants above it.
Subscription sites are exposed here because buyers forget recurring charges and dispute them. Clear billing descriptors, easy cancellation, renewal reminders and fast refunds on request all keep your ratio down. A refund costs you one sale; a dispute costs the sale, a fee and a mark against your account.
What happens when a processor pulls out?
Payment pressure on adult content is not theoretical. In July 2025, itch.io deindexed all adult NSFW content from its browse and search pages after scrutiny from its payment processors, following an advocacy campaign aimed at the card networks and processors. A whole storefront changed overnight because of where its money flowed.
For a single fan site the risk looks like this: a processor reviews your content, decides a character, tag or marketing angle crosses a line, and freezes the account. Pending payouts and the reserve are held, recurring subscriptions stop renewing, and your ad spend keeps running into a checkout that no longer works. The operators who come through this intact share three habits:
- They hold at least two card relationships. A second approved biller or MID, already integrated and tested, so traffic can be switched in hours rather than weeks.
- They keep content inside the strictest rule set. If one processor would object, they treat it as off limits everywhere.
- They keep cash outside the reserve. At least a couple of months of operating costs that do not depend on the next payout.
How to choose a payment processor for your fan site
Use these questions when you compare offers. Get the answers in writing.
- Does it explicitly accept AI-generated adult content? Some billers that accept live-action adult content are cautious about AI. Ask directly and describe your product honestly; a surprise after approval is worse than a no now.
- Who is the merchant of record? With a biller acting as merchant of record, its name usually appears on the card statement and it handles much of the compliance and customer service. With your own MID, you control more and owe more.
- What is the reserve, and when does it release? Percentage, holding period and whether it can step down after a clean track record.
- How are recurring charges priced? Verotel's public terms add 1.5 points to recurring transactions; others price differently. On a subscription site this matters more than the headline rate.
- What are the dispute fees and the termination triggers? Know the chargeback level that gets you a warning and the level that gets you closed.
- Which countries and card types are supported? A biller that declines a large share of your traffic's cards is expensive no matter what the rate says.
- What does the checkout look like? Hosted pages, one-click upsells for tips and unlocks, saved cards and cancellation flows all affect conversion and disputes.
- How does it handle refunds and cancellations? Self-serve cancellation reduces disputes, which protects your account.
Is crypto a real alternative for fan site payments?
Crypto solves two problems: no card chargebacks and no card brand content review. Gateways such as NOWPayments publish fees of around 1% per transaction, well below what adult card billing tends to cost. For buyers who already hold crypto, it can be a smooth checkout.
The catch is conversion. Most paying fans want to use a card, and very few will buy a wallet and fund it to unlock a chat. Crypto works best as a second rail: an option at checkout, a fallback during a card outage, and a way to serve buyers in regions where cards decline. It does not replace a card processor for a consumer subscription business. We cover the setup in more detail in our guide to crypto payments for fan sites.
Two cautions. Crypto gateways have their own acceptable use policies, so read them before assuming adult content is fine. And crypto revenue is still revenue for tax and accounting purposes in most places, so you need clean records of every sale and conversion.
Should you run your own merchant account or use a platform?
There are two realistic ways to get paid for an AI companion site.
Run billing yourself. You apply to adult billers and high-risk acquirers in your company's name, pay registration fees, fund the reserve, build the moderation and age-verification processes the networks expect, monitor disputes, and keep a backup ready. You keep the full margin after fees, and you carry all of the risk and admin. For a deeper look at the application process, see our guide to high-risk merchant accounts for adult content.
Use a white-label platform that runs billing for you. The platform holds the processor relationships, compliance processes and backup rails, and pays you a share of revenue. You give up some margin and gain a working checkout from day one, plus no reserve sitting on your own balance sheet. WhiteLabelFans works this way: approved partners launch a branded AI companion site and keep up to 60% of total site revenue across subscriptions, tips, unlocks and upsells, with payouts on a regular schedule, while the platform handles the payment stack. If you are weighing the two routes, our white-label AI companion platform overview and earnings breakdown lay out the trade-offs.
The right choice depends mostly on your traffic. Operators with steady volume, working capital and appetite for compliance can do well running their own billing. Affiliates and creators whose strength is audience, not payments, usually earn more by focusing on traffic and letting someone else carry the processor risk.
A launch checklist for fan site payments
- Confirm in writing that each processor accepts AI-generated adult content and your specific niches.
- Register under the correct category code (MCC 5967 for adult content) and budget for Visa and Mastercard registration fees.
- Document your moderation: pre-publication review, banned prompts and tags, adult-only characters, and a removal request process.
- Set a clear billing descriptor, renewal reminders and self-serve cancellation to keep disputes low.
- Model the rolling reserve against your traffic plan and hold enough cash to cover it.
- Integrate a second card option and a crypto rail before you need them.
- Review dispute and fraud ratios weekly against the network thresholds.
Frequently asked questions
Can I use Stripe or PayPal for an AI girlfriend site?
No, not for explicit content. Stripe's restricted businesses list prohibits pornography, adult live chat and pay-per-view, and explicitly includes AI-generated content that meets those criteria. PayPal does not permit sexually oriented digital goods, including website subscriptions. Using either for an adult AI site risks a frozen account and held funds.
What payment processor do adult fan sites use?
Most use adult-specialist billers such as CCBill, Segpay, Epoch or Verotel, or a direct merchant account through a high-risk acquirer. Many add a crypto gateway as a secondary option. Large platforms often run more than one card relationship so they can reroute payments if a provider changes its terms.
How much is a rolling reserve for an adult merchant account?
It varies by processor and risk profile, and is usually negotiated. Verotel's public merchant agreement holds 10% of customer charges for 26 weeks. On $30,000 a month in card sales, that structure builds a reserve of roughly $18,000 by month six, so plan working capital around it.
Do card networks allow AI-generated adult content?
Yes, under rules. Visa's updated integrity risk standards require merchant category code 5967 for adult content, including AI-generated adult content. Mastercard's adult content standards require pre-publication review, a complaints and removal process, and no marketing that implies minors or nonconsent. Processors expect you to show how you meet these.
Is crypto enough to run a fan site without a card processor?
Rarely. Crypto gateways cost around 1% and carry no card chargebacks, but most fans prefer to pay by card and will not set up a wallet to subscribe. Use crypto as a backup rail and for buyers who ask for it, alongside at least one card processor.
What chargeback rate gets an adult merchant in trouble?
Under Visa's Acquirer Monitoring Program, the merchant excessive threshold dropped to 1.5% on April 1, 2026, with an $8 fee per dispute and fraud report above it. Individual processors often act earlier than the network does, so treat any rising dispute trend as urgent.
Sources
- Stripe: Prohibited and restricted businesses
- PayPal: Policy on sexually oriented goods and services
- CCBill: Pricing
- Verotel: Merchant Agreement
- CCBill: Mastercard Standards for adult content merchants
- LegitScript: Adult, escort and dating merchants and the VIRP updates
- Chargeback Gurus: Visa announces even more VAMP changes
- GamingOnLinux: itch.io deindexes adult content after payment processor scrutiny
- NOWPayments: Pricing
WhiteLabelFansThe partner team behind the WhiteLabelFans platform, writing from what we see running AI companion sites for operators. About us · Updated
Essential guides: White label AI companion platform · Candy AI clone vs white label · How AI companion sites earn · Launch niches